7 min read
The Maryland Appraisal Clause: A Plain-English Guide for Homeowners and Property Owners
What the appraisal clause in a Maryland property policy actually says, when it makes sense to use it, and the traps to avoid along the way.
Independent property claim appraisal · Statewide
When the insurer agrees the damage is covered but the check won’t pay for the repair, Maryland Insurance Appraiser builds an independent, measured valuation and carries it through the appraisal clause in your policy.
Retained by you — never by the insurer
Why owners call
Most short claims aren’t denials. A rowhouse roof priced as a patch, plaster walls estimated as drywall, a matching problem nobody mentioned, a code upgrade Baltimore County will require anyway. A Maryland Insurance Appraiser exists for those differences.
Services
Start with a review of the insurer’s estimate, bring us in after appraisal has been demanded, or appoint us as a neutral umpire. Swipe or use the arrows to browse.
 01
We serve as your appointed appraiser once you or your insurer invokes the appraisal clause on a Maryland property claim.
 02
Independent appraisal for underpaid homeowners and condo claims, from Baltimore rowhouses to Deep Creek Lake cabins.
 03
Appraisal for condo associations, HOAs, landlords and business owners with large or multi-building property losses.
 04
Appraisal for hail and roof claims where the carrier pays for spot repairs but the roof really needs replacement or matching.
 05
Appraisal for derecho, straight-line wind and tornado losses – roofs, siding, framing and the debris left behind.
 06
Appraisal for wind-driven losses from hurricanes, tropical storms and nor’easters along the Bay, the coast and inland.
 07
Appraisal for burst pipes, appliance leaks and storm-driven water losses where drying, tear-out or rebuild costs are disputed.
 08
Appraisal for fire, smoke and soot losses, including rowhouse fires that spread through party walls to neighboring homes.
 09
Appraisal for snow-load roof collapse, ice-dam leaks and frozen or burst pipes – worst in Garrett and Allegany counties.
 10
Appraisal for oaks, tulip poplars and big limbs that land on roofs, decks, fences and garages after Maryland storms.
 11
A line-by-line review of your insurer’s estimate before you decide whether demanding appraisal is worth it.
 12
Impartial umpire service for Maryland property appraisals when both party appraisers jointly ask us to serve.
Fit check
Appraisal answers one question: how much the covered damage costs. It is powerful for that question and useless for others.
The process
The appraisal clause turns an open-ended argument into a short, defined procedure with a binding result.
We read the policy, the insurer’s estimate and your photos, then say plainly whether appraisal fits.
An independent inspection and measured, line-item estimate priced for your Maryland ZIP code.
Appraisal is invoked in writing and your appraiser is named inside the policy’s time limit.
Your appraiser works item by item with the insurer’s appraiser. Most gaps narrow here.
Anything unresolved goes to a neutral umpire. Two signatures set the amount of loss.
Five claim climates
Lake-effect snow near Deep Creek, hail in the Frederick Valley, rowhouse fires in Baltimore, hurricane deductibles on the Bay, salt and surge in Ocean City. Hover or tap a region.
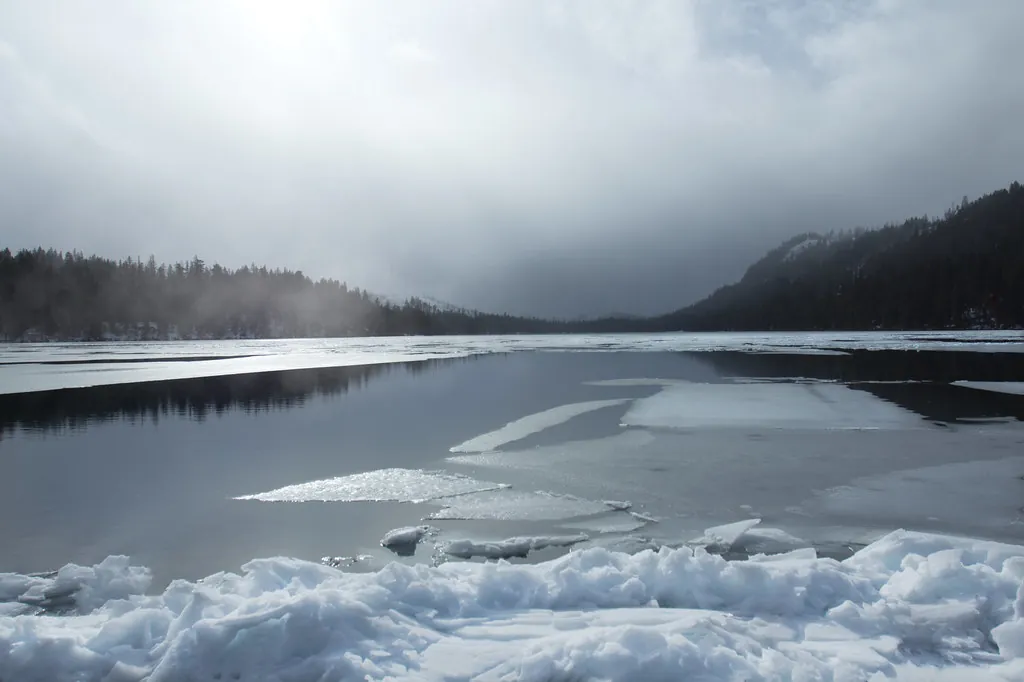
Garrett · Allegany · Washington
Mountain snow, ice dams and frozen pipes in seasonal cabins; hail rolling off the ridges into the Hagerstown Valley; river flooding along the Potomac and its creeks.
Oakland, Deep Creek Lake, Frostburg, Cumberland, Hancock, Hagerstown
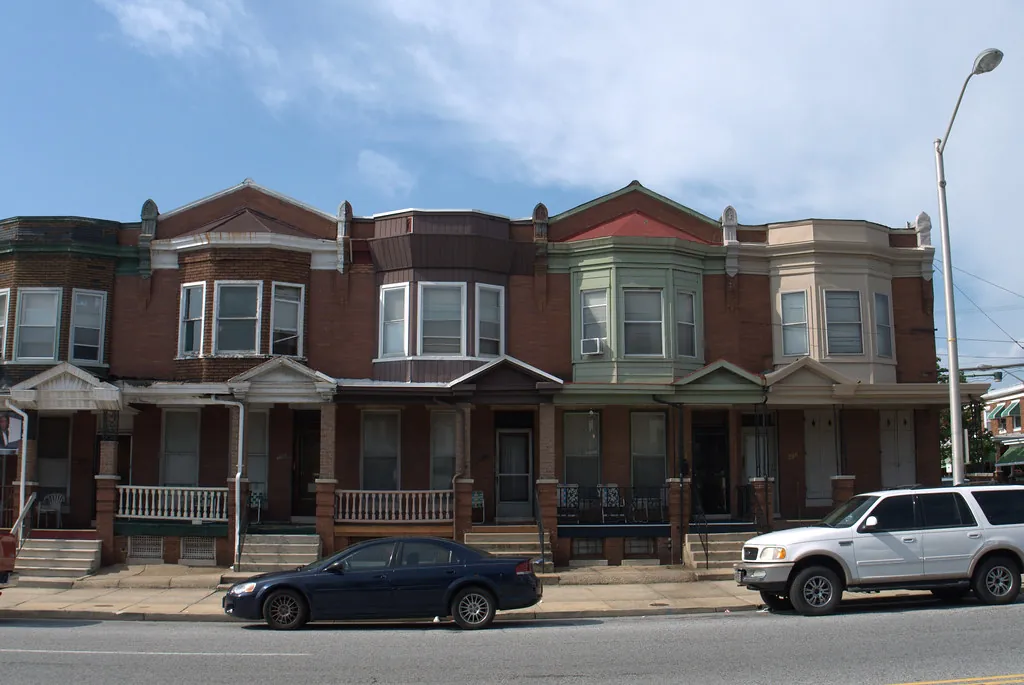
Baltimore City · Baltimore Co. · Howard · Anne Arundel · Harford · Carroll
Brick rowhouses with low-slope roofs and shared party walls, flash floods in stream valleys like Ellicott City’s, derecho-felled oaks and spring hail in the northern suburbs.
Baltimore, Towson, Catonsville, Ellicott City, Columbia, Annapolis, Bel Air, Westminster
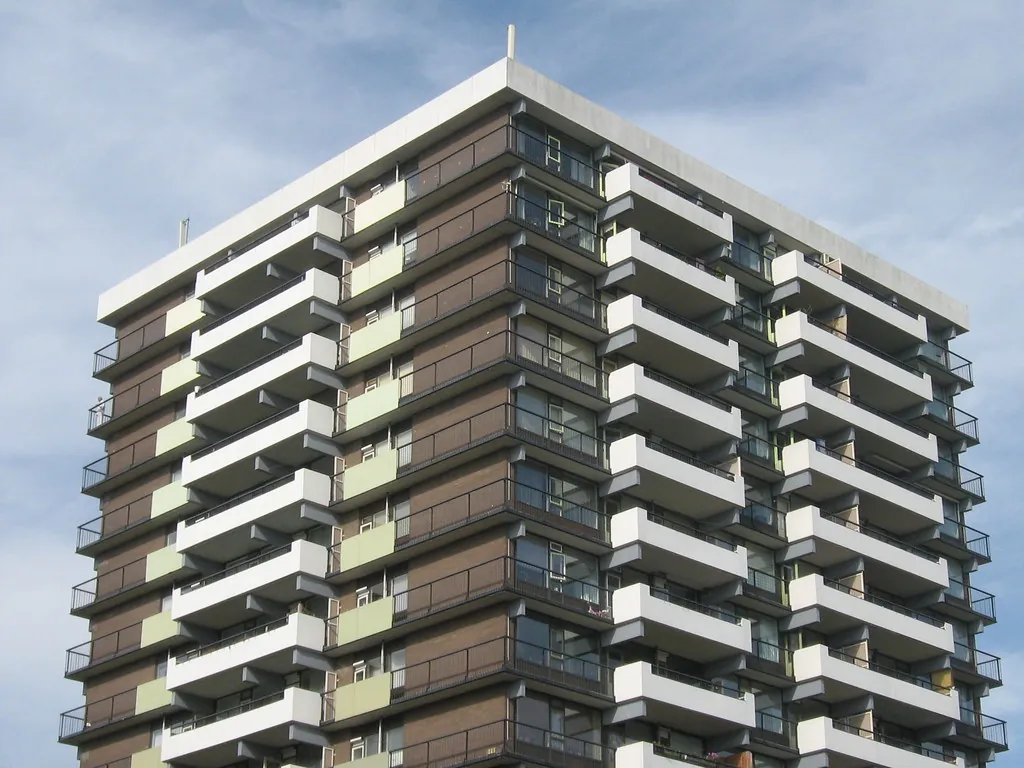
Montgomery · Prince George’s · Frederick
High-rise condos and HOA communities, 1950s–60s ramblers, big tree canopies that come down in derechos, and hail in the Frederick Valley.
Rockville, Silver Spring, Gaithersburg, Bowie, Laurel, Frederick, Urbana
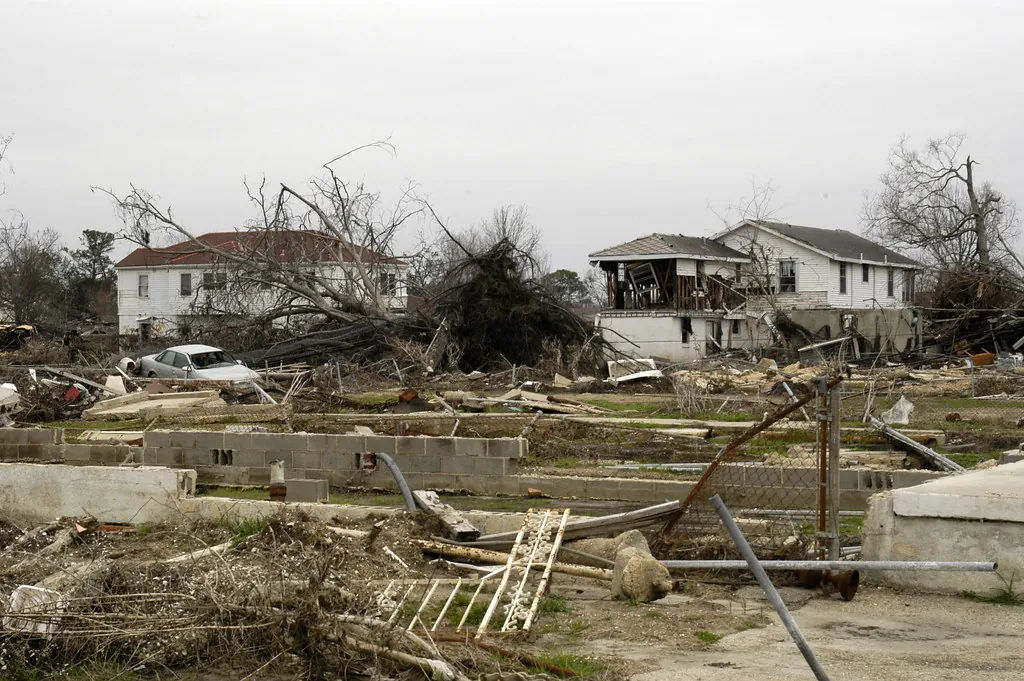
Charles · Calvert · St. Mary’s
Tornado history around La Plata, tropical-storm wind and tidal flooding on the Patuxent and Potomac shores, and fast-growing subdivisions around Waldorf.
Waldorf, La Plata, Prince Frederick, Solomons, Lexington Park, Leonardtown
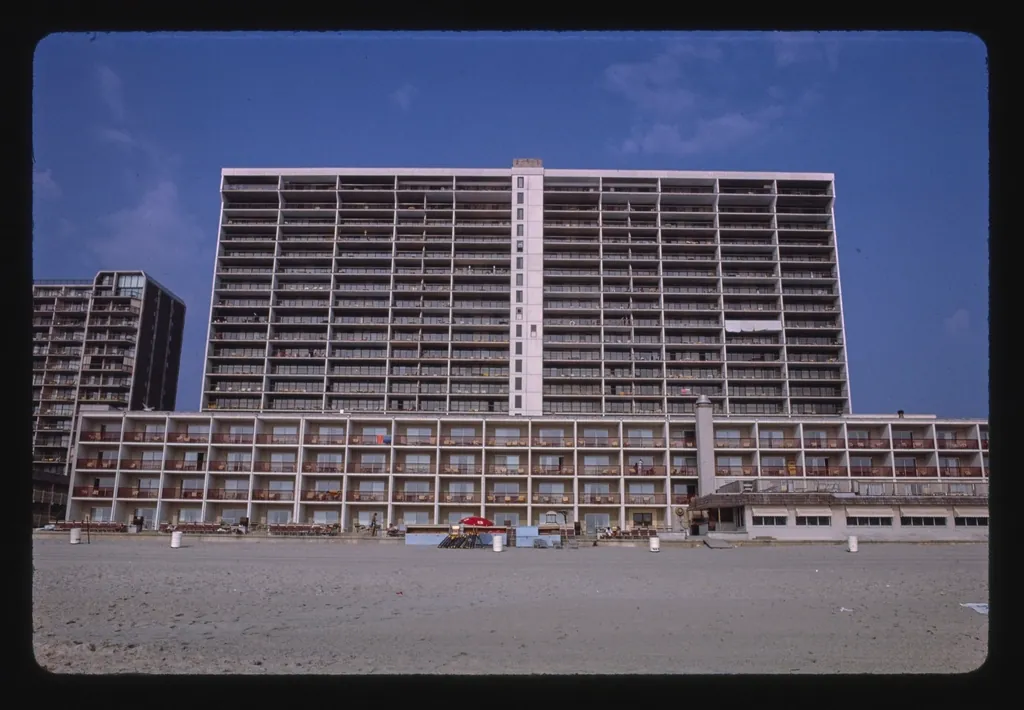
Nine counties from Cecil to Worcester
Hurricane and named-storm deductibles, wind-driven rain, low-lying farmland and waterfront towns, and salt-air wear on Ocean City’s condo towers.
Elkton, Chestertown, Easton, Cambridge, Salisbury, Crisfield, Berlin, Ocean City
Free & private
Check the insurer’s math before you call anyone. Every tool runs in your browser — nothing is stored or sent.
Enter the insurer’s estimate and your contractor’s. If the gap is wide, a Maryland Insurance Appraiser conversation makes sense; if it’s narrow, a documented supplement may close it faster.
Want fees included? Open the full claim gap & fee estimator.
Where we work
We take claims in every county and Baltimore City. These twelve communities have their own pages with local housing and storm history.
 BaltimoreBaltimore City (independent city)
 TowsonBaltimore County
 Ellicott CityHoward County
 AnnapolisAnne Arundel County
 FrederickFrederick CountyRockvilleMontgomery County
 BowiePrince George’s CountyWaldorfCharles County
 HagerstownWashington CountyCumberlandAllegany CountySalisburyWicomico CountyOcean CityWorcester County
Choosing help
Each solves a different problem. Picking the right one first saves time and fees.
| Question | Maryland Insurance Appraiser | Public adjuster | Attorney |
|---|---|---|---|
| Main job | Value the amount of loss | Prepare & negotiate the claim | Legal rights, disputes, litigation |
| Best moment | Coverage accepted, number disputed | Early, from first notice | Denials, bad faith, deadlines |
| Result | Award signed by 2 of 3 | Negotiated settlement | Settlement or judgment |
| Decides coverage? | No | No | Argues it |
Questions
Straight answers on process, cost and when appraisal is the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, build an independent line-item estimate, work through the differences with the insurer’s appraiser and, if needed, present unresolved items to a neutral umpire.
No. An MIA complaint asks the regulator to look at how the insurer handled your claim. Appraisal is a process in your policy that sets the amount of loss. They are separate tracks, and an attorney can tell you how they interact in your situation.
When coverage has been accepted, you have the insurer’s estimate, and the gap between it and a qualified contractor’s estimate is meaningful — often more than 10% or several thousand dollars.
On the amount of loss, generally yes, once two of the three panel members sign. That’s why the documentation behind your number matters so much before anyone invokes appraisal.
Each side pays its own appraiser and usually half of the umpire’s fee. We put our fee in writing before any work starts, and the first conversation is free.
Yes. We take claims in all 23 counties and Baltimore City — Western Maryland, the Capital Region, Southern Maryland and the Eastern Shore included.
Knowledge base
Practical, Maryland-specific guides from the Maryland Insurance Appraiser knowledge base.
7 min read
What the appraisal clause in a Maryland property policy actually says, when it makes sense to use it, and the traps to avoid along the way.
7 min read
A Maryland Insurance Administration complaint and an appraisal demand solve different problems. Here’s how to tell which one your claim needs.
8 min read
Low-slope roofs, shared parapets and old plaster make Baltimore rowhouse claims unusually easy to underestimate. Here’s what to document and why.
Before you sign the release
A short review now can keep you from accepting a settlement that won’t cover the repair.
Start a conversation
Tell us what happened and what the insurer offered. We’ll review it and give you an honest read on whether appraisal is worth pursuing.